
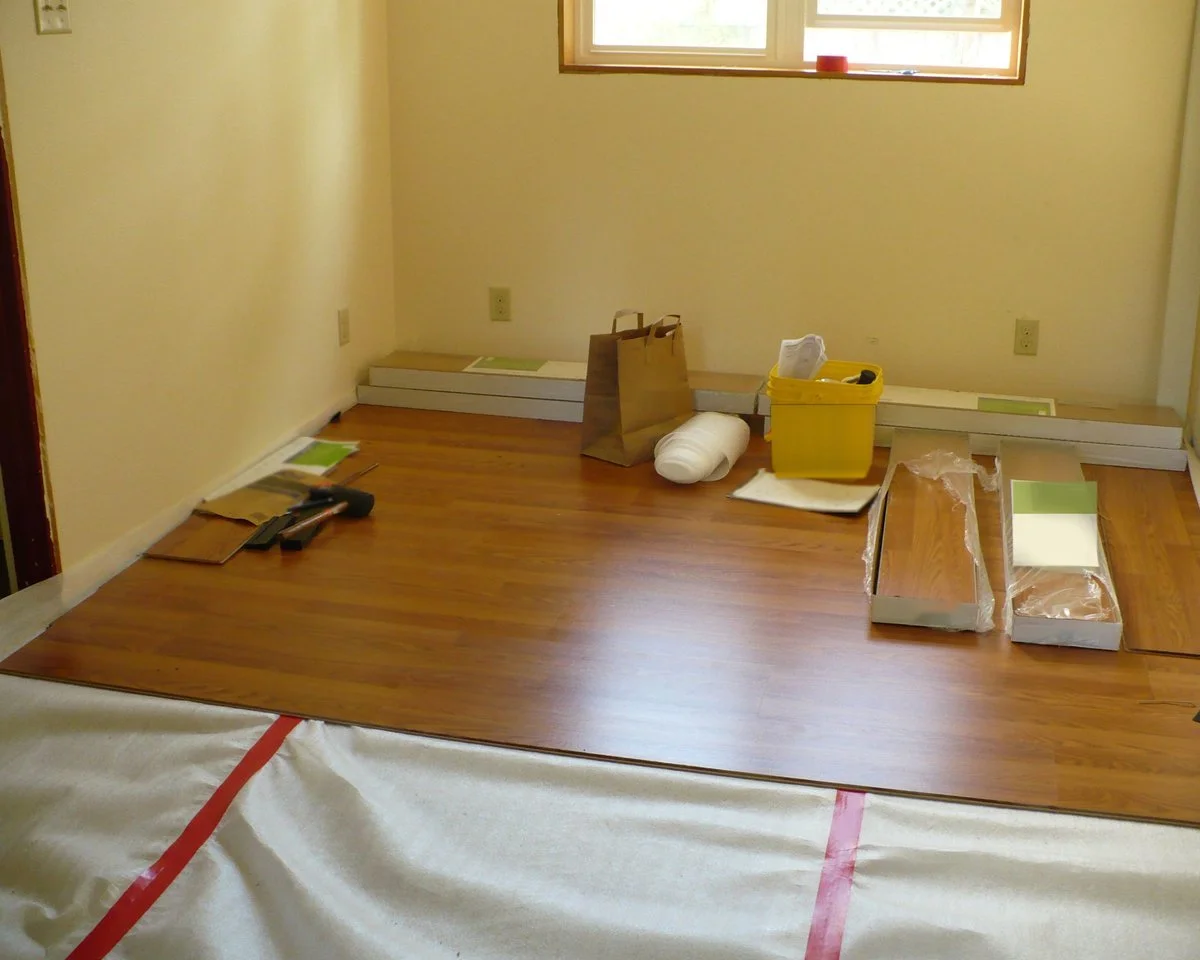
Photo: Suzcp6 / Wikimedia Commons, ‘Halfway to done’, CC BY-SA 4.0, modified
You are halfway through a plank install in a customer's living room. A helper drags a box of flooring across the kitchen and gouges the finished floor you were not hired to touch. Or an HVAC tech sets a ladder against a quartz countertop and it cracks. Or an electrician fishing wire through a wall punches into the neighbor's side of a shared wall.
Nobody is hurt, but the customer's property is damaged, and the job is not done yet.
Education only, not legal advice. What can be placed depends on the policy, the risk, and underwriting.
One problem: you work inside someone else's space
Flooring installers, HVAC techs and electricians spend most of their day inside occupied homes, offices and shops. That is different from working on an empty lot. The customer's furniture, finishes, fixtures and walls are all within reach while the work is underway:
- Scratched or gouged floors outside the work area
- A cracked countertop, tub or tile from a dropped tool or a ladder
- Drywall, trim or a ceiling damaged while running wire or duct
- Paint, rugs or furniture stained by adhesive, dust or a spill
How damage like this is usually handled in general liability depends on the policy, its limits, and its exclusions. Damage to the customer's other property is often discussed differently from the work you are doing itself, and from property in your care, custody or control. Those details matter, and they are worth walking through before the next job, not after a call from an upset customer.
If the damage shows up after you leave, that is the completed-work side, covered in our post on finished work. This post is about while you are still on the job.
A Farmers-safe answer (plain words)
At SDL Commercial Insurance (Samuel D Landers Agency, a Farmers appointment), we start with where you actually work and what is around you, then talk through what Farmers can usually place for that risk. Here is what usually comes up:
- Where you work. Occupied homes, multi-unit buildings, offices, restaurants or retail. High-end finishes and occupied commercial spaces usually get more questions.
- How the GL policy treats damage during the job. We walk through how the policy handles damage to the customer's property, the limits that apply, and exclusions that matter for your trade, including the work itself and property in your care.
- One bad incident, sized. The Coverage Calculator's general liability worksheet asks for a single-incident loss you want to plan for. Pick a scenario, like replacing a run of hardwood or a countertop, and see what one event could look like. It is a planning worksheet, not a quote, a binder, or a rate.
- Your crew and your subs. Who works inside the customer's space, and whether a sub carries their own coverage.
- Simple habits. Floor protection, before photos, and a walk-through with the customer at the start. Good habits do not change what a policy covers, but they make any conversation clearer.
None of this is a guarantee of terms. We place Farmers products only; we do not shop other carriers.
What to bring to the call
- Business name, entity type and CSLB classification
- Your usual job mix and the kinds of spaces you work in
- Current general liability policy or renewal notice
- Any contract pages about damage to the customer's property
- Planning numbers from the Coverage Calculator, if you ran it
Bring what you have. We sort the rest on the call.
In force or not yet
Have an in-force policy we can write from? We issue the certificate from it. No policy yet? Book, bind, then certificate. A certificate is issued only after coverage is bound and in force, never ahead of it.
Next step
Coverage Calculator (planning only, not a quote)
Or call (408) 876-7107
Samuel D Landers · California Insurance License #4538988 · SDL Commercial Insurance · Samuel D Landers Agency
