
Photo: National Park Service (public domain), via Wikimedia Commons.
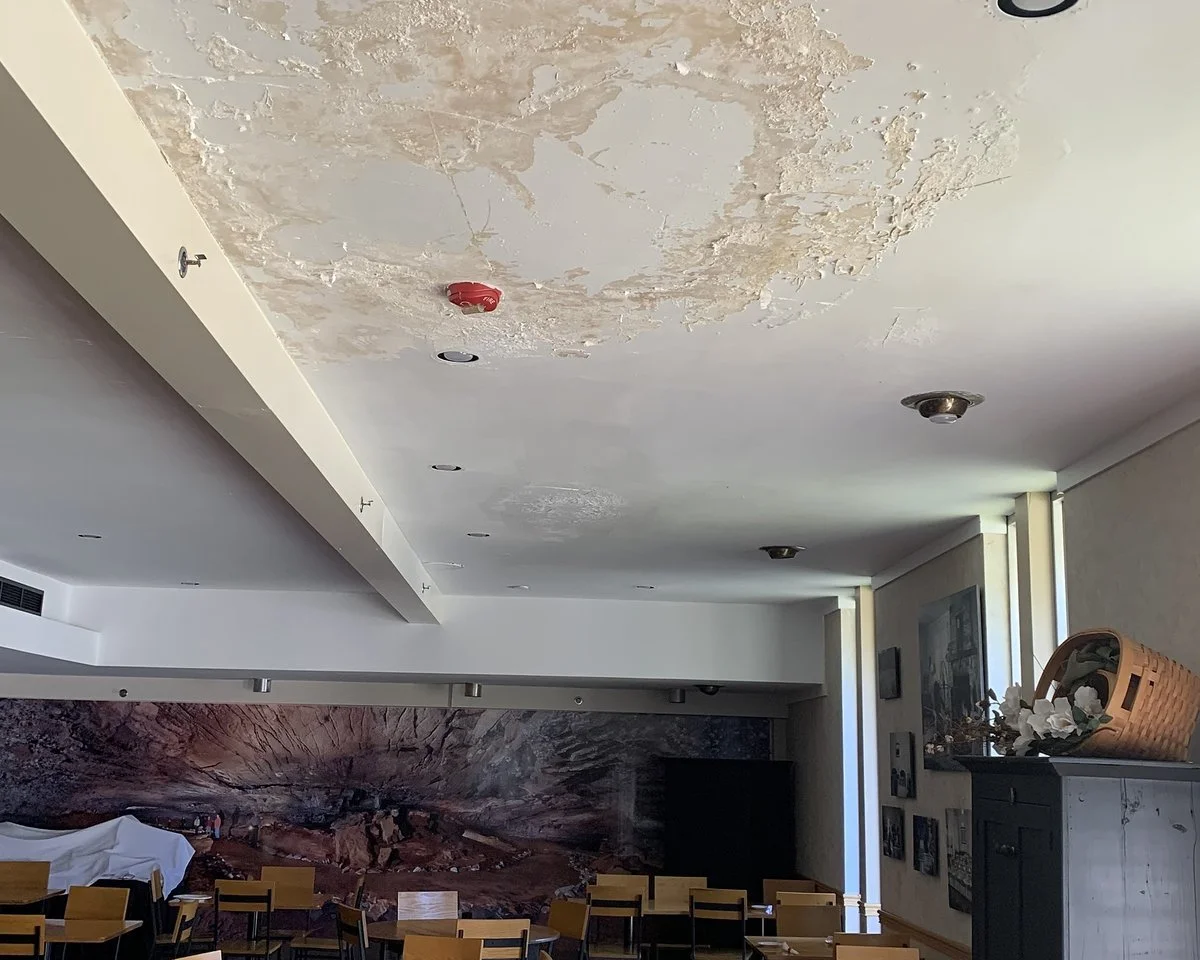
It is Monday morning in a small two-story office building. A sprinkler line above Suite 204 cracked over the weekend. Water came through the ceiling tiles in 204, ran down the walls into 104 below, and soaked the carpet in the shared hallway. Three tenants are calling the owner at once, and each one is asking the same thing: whose insurance handles this?
In a multi-tenant building, the honest answer is usually "it depends," and the time to sort out what it depends on is before the leak, not during it.
Education only, not legal advice. What can be placed depends on the policy, the risk, and underwriting.
One problem: one leak, several policies, and nobody has compared them
When water moves from one suite into others, more than one policy and more than one document may be part of the conversation:
- The owner's building policy, for the structure and the owner's property
- Each tenant's own policy, for their contents, equipment and improvements
- The lease, which may say who is expected to insure what and who handles repairs
- The cause of the leak itself, since many policies treat sudden water damage differently from slow seepage, wear or lack of maintenance
How these fit together depends on the policies and the lease wording. We are not lawyers and do not interpret leases. What an owner can do is know ahead of time what the building policy is set up to handle, and what it is not.
A Farmers-safe answer (plain words)
At SDL Commercial Insurance (Samuel D Landers Agency, a Farmers appointment), we start with how the building is laid out and who occupies it, then talk through what Farmers can usually place for the owner. Here is what usually comes up:
- What the building policy is for. The structure, building systems and the owner's own property. How water damage is treated depends on the policy and the cause, so we read that part with you.
- What tenants are expected to carry. Tenants usually insure their own contents and equipment. Who insures tenant improvements often depends on the lease, so bring it and ask your attorney about any wording questions.
- Shared areas and building systems. Hallways, restrooms, the roof, plumbing and sprinkler lines may be the owner's to maintain, depending on the lease. We talk through how they appear on the policy.
- Income while suites are repaired. If a tenant cannot use a suite during repairs, rent can stop depending on the lease. We covered that side in lost rental income for building owners.
- Maintenance records. Sprinkler inspections, plumbing service and roof work can matter when the cause of a leak is reviewed. Keep them together.
Knowing this ahead of time does not change what happens in a claim, and it does not promise a particular outcome. It helps you answer tenants calmly on a bad Monday. None of this is a guarantee of terms. We place Farmers products only; we do not shop other carriers.
What to bring to the call
- Business name, entity type and who owns the building
- Building address, square footage, construction and year built
- A tenant list with suite numbers and what each tenant does
- A copy of a typical lease (we look at the insurance section; your attorney handles the rest)
- Sprinkler, plumbing and roof service records
- Current building policy or renewal notice
Bring what you have. We sort the rest on the call.
In force or not yet
Have an in-force policy we can write from? We issue the certificate from it. No policy yet? Book, bind, then certificate. A certificate is issued only after coverage is bound and in force, never ahead of it.
Next step
Book a call → https://www.sdlcommercialinsurance.com/schedule?utm_source=blog&utm_medium=organic&utm_campaign=blog_oct28
Or call (408) 876-7107
Samuel D Landers · California Insurance License #4538988 · SDL Commercial Insurance · Samuel D Landers Agency
