
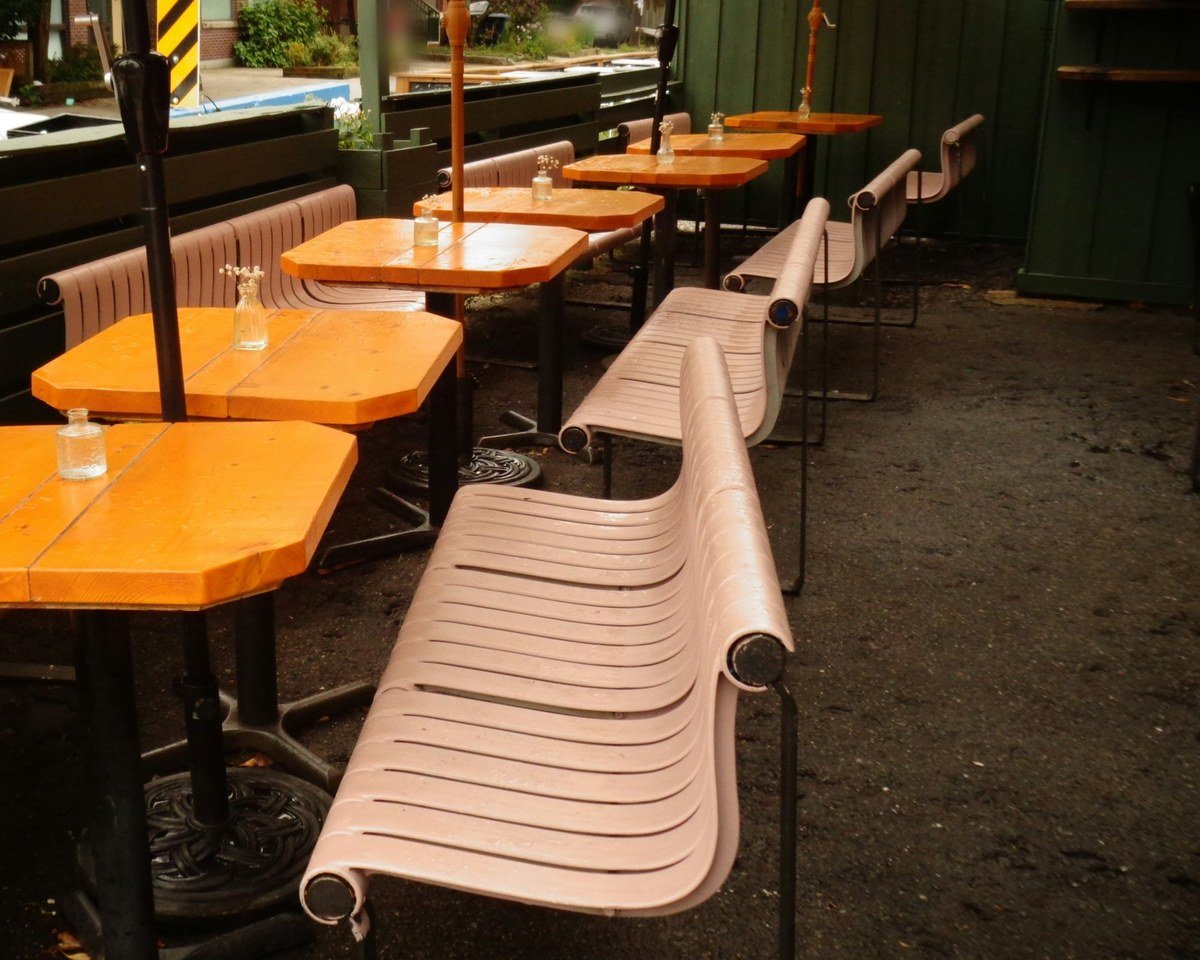
A café on a busy Bay Area block has six tables inside and a line out the door on weekends. The owner wants to add a parklet: a wooden deck in two parking spaces out front, with planters along the edge and a few bistro tables. Another restaurant down the street just wants four two-tops on the sidewalk.
Both get the same packet from the city, and somewhere in it is a line about insurance: a certificate, certain limits, and who needs to be named.
Education only, not legal or permit advice. What can be placed depends on the policy, the risk, and underwriting.
One problem: the permit asks for a certificate the policy may not show yet
Outdoor seating moves part of your dining room onto public space. Many city outdoor dining programs ask for proof of general liability before a permit is issued or renewed, and some want the city named on the certificate in specific words. What any one city asks for varies, and requirements change, so the permit packet is the source to read, not a blog post.
Where restaurants usually get stuck:
The permit packet asks for limits or wording nobody has compared to the current policy
The parklet was built after the last renewal, so the policy describes only the indoor space
Seating, heaters or string lights were added, and nobody mentioned them
Beer and wine now go out to the sidewalk tables
A Farmers-safe answer (plain words)
At SDL Commercial Insurance (Samuel D Landers Agency, a Farmers appointment), we start with the permit packet and the seating you actually have, then talk through what a Farmers policy can usually show for that risk. Here is what usually comes up:
Read the permit's insurance section together. Bring the page that lists limits, who must be named, and any wording the city wants on the certificate. We compare it with what your policy actually says.
Describe the seating as it is. Parklet deck or sidewalk tables, how many seats, hours of use, and anything that sits on it: planters, heaters, umbrellas, lighting or barriers.
Who built it and who maintains it. Whether a contractor built the parklet, and who sets up, cleans and breaks it down each day.
Who serves, and your house practices. Who pours, whether they hold current responsible beverage service (RBS) certification, and how you check IDs. California ABC sets its own RBS rules, so check with ABC for what applies to you. We note these to describe the risk; this is not legal or compliance guidance.
Plan the numbers before the call. The Coverage Calculator's general liability worksheet lets you enter a client or lease insurance requirement and the limits it asks for, so you can see the gap on paper. It is a planning worksheet, not a quote, a binder, or a rate.
Indoor equipment and spoilage are a separate talk, covered in kitchen claim vs storefront.
None of this is a guarantee of terms. Availability, limits, exclusions and conditions apply. Whether a policy can name the city, and in what wording, depends on the policy. We place Farmers products only; we do not shop other carriers.
What to bring to the call
Business name, address and the kind of food service
The outdoor dining permit packet, or the insurance page from the application
A simple sketch or photos of the parklet or sidewalk layout, with seat count and hours
What sits outside: planters, heaters, umbrellas, lights, barriers
Whether alcohol is served outside, and who serves it
Current general liability policy or renewal notice
Planning numbers from the Coverage Calculator, if you ran it
Bring what you have. We sort the rest on the call.
In force or not yet
Have an in-force policy we can write from? We issue the certificate from it. No policy yet? Book, bind, then certificate. A certificate is issued only after coverage is bound and in force, never ahead of it.
Next step
Coverage Calculator (planning only, not a quote) → https://calculator.sdlcommercialinsurance.com/
Book a call → https://www.sdlcommercialinsurance.com/schedule?utm_source=blog&utm_medium=organic&utm_campaign=blog_oct14
Or call (408) 876-7107
Samuel D Landers · California Insurance License #4538988 · SDL Commercial Insurance · Samuel D Landers Agency
